US wholesale inflation accelerated in July, rising the most in three years. The data indicates that prices rose faster for producers than consumers. The implication: importers are absorbing the cost of tariffs rather than passing them on to customers. “It will only be a matter of time before producers pass their higher tariff-related costs onto the backs of inflation-weary consumers,” wrote Christopher Rupkey, chief economist at fwdbonds, a financial markets research firm.
Author Archives: James Picerno
Momentum And High-Beta Equity Factors Lead Market This Year
The dominance of the momentum factor roars on. At nearly every step this year, this risk factor has outperformed the broad stock market, based on a set of ETFs through yesterday’s close (Aug. 13). The recent rebound in so-called high-beta stocks has lifted this factor to a strong second-place performer so far in 2025.
Macro Briefing: 14 August 2025
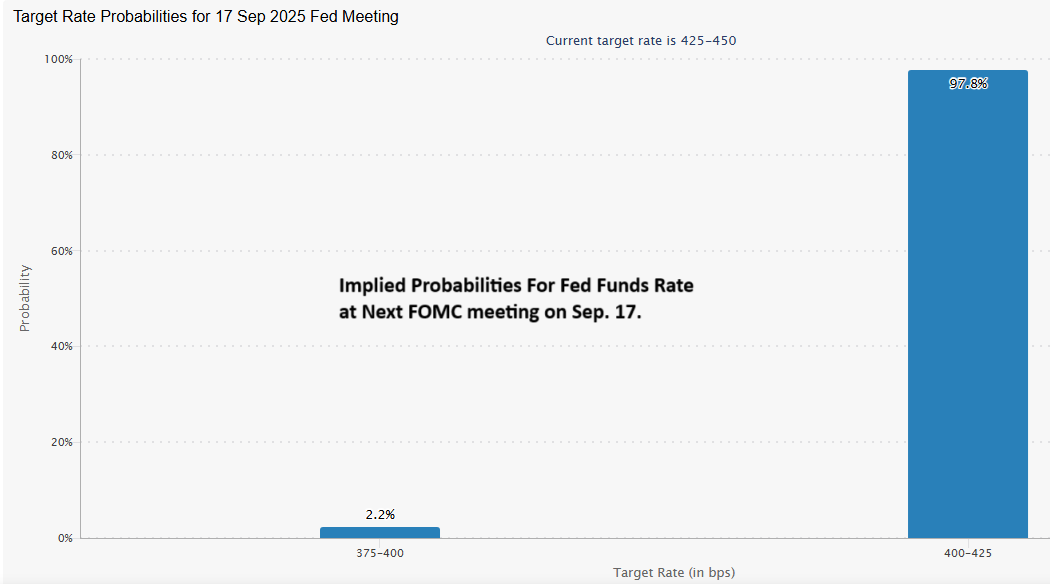
Fed funds futures are pricing in a near certainty of a rate cut at the next FOMC meeting on Sep. 17. The market expects a 1/4-point cut, which would reduce the current 4.25%-4.50% target range to 4.0%-4.25%. “The Fed has a difficult balancing act,” said Derek Horstmeyer, a finance professor at George Mason University’s Costello College of Business. “They have to weigh an expectation of slower job growth against an expectation of inflation. I think they’re weighing all of it.”
10-Year US Treasury Yield ‘Fair Value’ Estimate Steady In July
The “fair value” estimate for the 10-year US Treasury yield was basically unchanged in July, based on the average for three models run by CapitalSpectator.com. The market premium – the actual yield less the fair-value estimate — was also steady last month, holding a moderate spread.
Macro Briefing: 13 August 2025
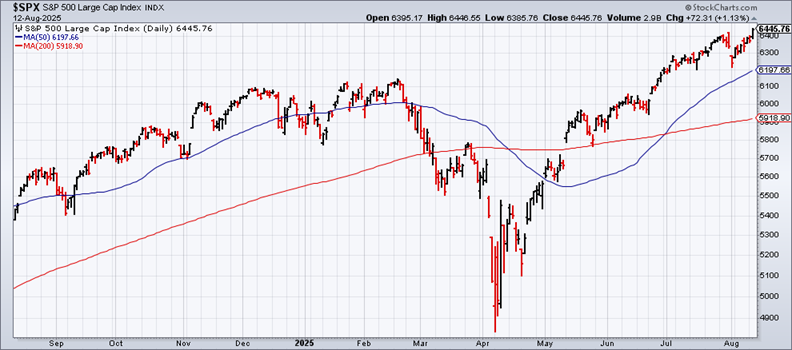
US stock market closes at another record high. The S&P 500 Index on Tuesday rallied 1.1%, marking a new all-time peak.
US Business Cycle Profile Shows Mixed Picture For Key Indicators
Using the US stock market as a guide suggests that business-cycle conditions remain strong in terms of the recovery since the current economic expansion began in May 2020. The rebound in equities is still one of the sharpest since 1970. But the stock market is not the economy, as the saying goes, and that’s where the analysis turns complicated, as suggested by a review of key economic indicators.
Macro Briefing: 12 August 2025
Trump extends trade truce with China for 90 days. The new deadline allows negotiations to continue ahead of a massive tariff hikes now set for Nov. 10. China also announced it is extending its pause on tariffs on the US.
Early Q3 US GDP Nowcasts Point To Economic Slowdown
Initial estimates of third-quarter economic activity indicate a downshift in output, based on the median for a set of nowcasts compiled by CapitalSpectator.com. Although the current numbers don’t anticipate recession conditions, the median estimate highlights a significant slowdown vs. Q2’s increase.
Macro Briefing: 11 August 2025
Nvidia and AMD to pay 15% of China chip sales to the US government. “The two chipmakers agreed to the financial arrangement as a condition for obtaining export licences for the Chinese market that were granted last week, according to people familiar with the situation, including a US official,” the FT reports.
Book Bits: 9 August 2025
● The Economic Consequences of Mr Trump: What the Trade War Means for the World
Philip Coggan
Q&A with author via MoneyWeek
Q: In your new book, The Economic Consequences of Mr Trump: What the Trade War Means for the World, you posit that president Donald Trump’s threats over tariffs are real, rather than a bluff, and represent a major threat to both the US and world economies.
A: Yes. Many investors seem to be assuming that Trump will ultimately back down from his threats of swingeing tariffs; markets have recovered from the collapse that took place in April when they were first announced. However, while there is still a chance that this could be correct, this attitude seems complacent.